


Reliance Industries (RIL) has recently staged a sharp recovery, gaining approximately 13% over the past month, including a nearly 12% single day rally following its Q2 FY27 results. Yet, despite this performance, a majority of actively managed Large Cap and Flexi Cap mutual funds entered the rally with significant underweight positions in the stock.
Have mutual funds underestimated Reliance’s comeback? And what could happen if they decide to close their underweight positions?
How Underweight Are Mutual Funds on Reliance?
When we analysed the RIL holdings of 61 Large Cap and Flexi Cap mutual fund schemes collectively managing approximately ₹8.7 lakh crore in AUM as of September 30, 2026, the numbers revealed a combined gross shortfall of ₹18,242 crore in RIL allocations relative to benchmark weights This represents the buying required for underweight funds to turn benchmark neutral. Interestingly, the combined ₹18,242 crore shortfall amounts to approximately 1% of RIL’s market capitalisation of ₹17.69 lakh crore.
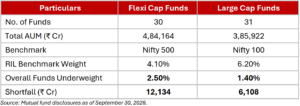
What Does This Mean?
Reliance’s recent rally raises an interesting question: Have mutual funds been caught on the wrong side of the trade? With significant underweight positions as of September-end, a sustained recovery in the stock could increasingly weigh on funds’ benchmark-relative performance.
And if fund managers begin closing these underweights, even partially, the resulting buying could be substantial. Could Reliance’s next leg of the rally be fuelled by the very funds that have largely stayed underweight?
Please note that the above should not be construed as an advice from us. Our company is in the business of distribution of suitable Financial Products to investors describing product specifications, material facts and the associated risk factors. We are acting as


